

Uber Pro Card

- 6.14K Reviews
- 4.9
- Downloads
- 1,000,000+
Our take on Uber Pro Card from Appgk
Uber Pro Card is a finance app from Branch Messenger built around a simple idea: making earnings from Uber work easier to manage after a driving or delivery shift. I found it most useful when treated as a focused money hub rather than as a complete replacement for every banking tool. The app is free, available to users aged Everyone, and its store summary is “Keep more of what you earn,” while the short description identifies it as Uber Pro Card.
That positioning matters. This is not a general budgeting app with a few driver-oriented extras added on. Its value comes from connecting the money side of Uber work with the routine decisions that follow: checking whether earnings arrived, moving through the available balance, using the card for work-related spending, and keeping personal finances separate from gig income. If you drive or deliver regularly, that narrower purpose can make the experience feel more practical than opening a conventional banking app and trying to reconstruct your workday afterward.
How I used it during a normal Uber workday
My baseline workflow was deliberately simple. I opened the app when starting a shift to confirm that I was looking at the right account, checked it after finishing to review the money available, and used the card account as a clearer boundary between Uber income and household spending. That separation is the first real advantage: it gives work earnings their own place instead of mixing everything into one balance.
A realistic example is an evening delivery shift. Before heading out, I would check the available balance and make sure the card was ready for the expenses I expected during the shift. Afterward, I could look at the account without scrolling through rent, groceries, subscriptions, and unrelated purchases. That does not replace a full income tracker, but it reduces the mental work involved in answering a basic question: how much of my Uber money is currently available?
Best Parts of Uber Pro Card
Things to Keep in Mind About Uber Pro Card
I also like the psychological benefit of using a dedicated account for gig work. When all income lands in a personal checking account, it is easy to spend it before remembering fuel, maintenance, taxes, or a slower week. Keeping the Uber-related money in its own place makes those obligations more visible. The app cannot make the budgeting decisions for me, but it gives those decisions a cleaner starting point.
The strongest workflow is therefore not “open the app constantly.” It is using it at consistent moments: before working, after working, and when deciding what portion of the balance can safely be used. Experienced users will get more from that rhythm than from repeatedly checking notifications or treating the balance as spendable profit.
News and Features Related to Uber Pro Card

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
The first settings and habits I would check
When I set up a finance app for regular work, I look for the options that affect everyday friction rather than changing every preference at once. With Uber Pro Card, I would begin by reviewing account access, card-related controls, notification choices, and the way balances or transactions are displayed. The goal is to make important activity noticeable without turning every small update into noise.
Notifications deserve a thoughtful approach. If alerts are too frequent, I tend to ignore them, which defeats their purpose. If they are too limited, I may not notice a balance change or card activity promptly. I would keep alerts that help me recognize meaningful account movement and reduce anything that merely encourages unnecessary checking. This is especially useful for drivers who work irregular hours and do not want their phone buzzing throughout a shift.
Don't want to read the full review?
I would also make the app easy to reach from the phone’s home screen. That sounds minor, but a finance tool becomes more useful when checking it takes a few seconds. A shortcut does not add a new feature; it simply supports the repeatable habit the app is best suited to. If I have to search through folders every time, I am more likely to postpone checking the account until the balance has become harder to interpret.
Another practical step is deciding in advance what the account is for. I would use it for Uber-related earnings and planned work spending, while keeping long-term household budgeting elsewhere if that is already working well. This prevents a common mistake: expecting a specialized card account to provide every function found in a full-service bank, budgeting package, or tax tool.
Screenshots
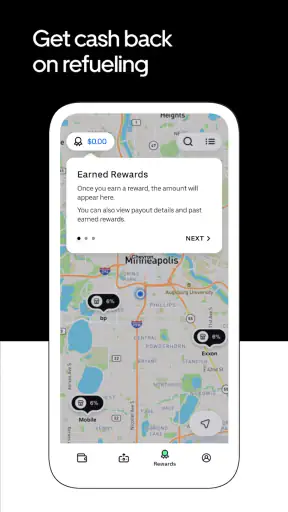
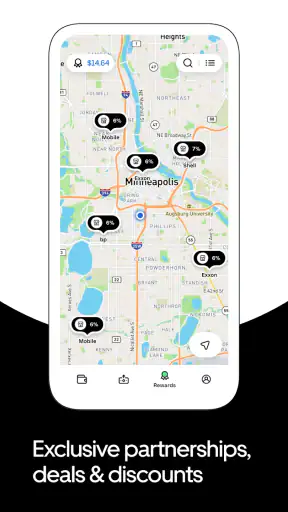
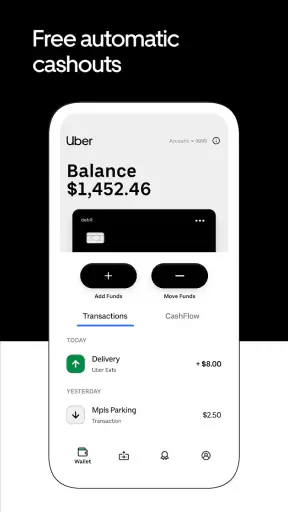
The app comes from Branch Messenger, and its finance focus is clear in the way I would approach it. I would not download it expecting investment tools, detailed category analysis, or a complete replacement for an established personal bank. I would judge it on whether it makes Uber income easier to access and organize. That narrower test is fairer and leads to a more useful setup.
Shortcuts that make the routine less tiring
The fastest pattern I found was to pair each app check with an existing event. For example, I could review the account when ending a shift rather than creating a separate reminder that might be ignored. I could also check it before transferring money into my personal spending routine or before paying for a work expense. Linking the app to a real decision is more effective than opening it out of habit.
I would keep a small note outside the app for recurring work costs and use the card balance as one part of that picture. Fuel, vehicle upkeep, phone costs, and taxes should not be confused with money that is genuinely available for personal spending. The app helps me see the account, but a separate record can still be necessary for expenses and tax preparation. That distinction is one of the most important trade-offs for independent workers.
A useful weekly pattern is to review the account at a fixed time, compare the balance with my own earnings and expense notes, and decide what can move into personal finances. This is better than making a decision after every trip because it reduces impulsive transfers and gives slower days some context. It also makes the balance less emotionally misleading: a high figure immediately after a busy period does not automatically mean high profit.
I would be careful about using the card for mixed purchases. If a transaction is partly personal and partly work-related, recording the reason immediately is easier than trying to remember it later. A dedicated account only improves organization when I preserve the separation. Otherwise, the same clutter that exists in a normal checking account gradually returns here.
For drivers who use more than one gig platform, I would also avoid assuming that this account automatically becomes a universal dashboard. The product is specifically presented around Uber Pro Card, so I would keep separate notes for other income sources unless my own setup clearly supports combining them. That may feel less convenient, but it prevents an incomplete picture of total earnings.
Where the app is genuinely useful
The clearest audience is an Uber driver or delivery worker who wants a dedicated place for earnings and everyday access to that money. It is especially appealing to someone who dislikes mixing gig income with a main bank account. Instead of forcing every work-related decision into a traditional checking account, the card gives the user a more focused routine.
It can also help someone who is new to tracking independent income. A beginner may not yet have a sophisticated spreadsheet or bookkeeping system, but can still create a basic separation between money earned through Uber and money already committed to household needs. That is a modest step, yet it can prevent accidental overspending.
I would recommend it less enthusiastically to someone who already has a reliable bank account, automated budgeting system, and detailed bookkeeping workflow that handles Uber income cleanly. In that situation, adding another account may create more reconciliation work than value. The app has to earn its place by reducing confusion, not merely by offering another balance to monitor.
It is also not the right central tool for someone seeking deep financial planning. If the main need is investment management, comprehensive tax reporting, complex household budgets, or a broad view of several financial institutions, a conventional banking or finance platform may be better. Uber Pro Card can sit alongside those tools, but I would not make it carry responsibilities it was not designed to handle.
What the strong reception tells me—and what it does not
The app has an average rating of 4.9 from around eighty-two thousand ratings, with roughly six thousand reviews, and it has passed one million installs. That level of adoption suggests that the focused experience resonates with many people who use it. I see it as evidence that the basic workflow is solving a real problem for a substantial driver audience.
At the same time, a high rating should not be treated as proof that every financial situation will fit the product. A driver who wants a separate work account may have an excellent experience, while someone who needs detailed accounting may still find it limited. Ratings reflect many individual contexts; my own recommendation depends on whether the app’s narrow purpose matches the user’s routine.
The app is free, which makes trying that workflow easier because there is no purchase decision to justify first. Even so, “free” does not remove the need to understand how the account fits with other financial services or personal obligations. I would still read the in-app terms and review the relevant account details before making it the main place for work earnings.
Its current version is 2026.8.2, and it requires Android 10 or later. That requirement is reasonable for many modern phones, but it matters if a driver relies on an older device. I would check compatibility before planning a shift around the app, especially if the phone is already struggling with updates or storage.
Limits that become clearer with regular use
The biggest limitation is scope. A dedicated Uber earnings card can simplify access and separation, but it does not automatically turn irregular gig income into a complete financial plan. I still need to think about operating costs, taxes, emergency savings, and personal spending. The app can support those habits, but it cannot replace them.
A second limitation is the risk of creating a second layer of administration. If I already use a main bank, a budgeting app, and a spreadsheet, every additional account requires attention. I would only keep the card in my routine if the separation genuinely saves time or prevents mistakes. Otherwise, the convenience of a specialized account may be outweighed by reconciliation work.
There is also a behavioral limit. Seeing money available after a shift can make it feel like disposable income, even though part of it may belong to future vehicle costs or tax obligations. I would treat the displayed balance as cash position, not profit. That single distinction protects the usefulness of the app more than any shortcut.
Security habits matter as well. I would use a strong device lock, avoid sharing access, and review account activity when something looks unfamiliar. Those are ordinary precautions, but they are particularly important when a card is connected to money earned through frequent, time-sensitive work. Convenience should never mean ignoring account awareness.
Finally, I would not rely on any one app as the only record of my financial history. Keeping receipts, mileage information, and expense notes in an organized place remains sensible for anyone working independently. The card can make transactions easier to see, but good records require a wider process.
My verdict for drivers choosing a money routine
After using Uber Pro Card as a focused work-money account, I see its main strength clearly: it reduces the distance between earning through Uber and managing those earnings in a separate, accessible place. The experience makes the most sense when paired with repeatable habits, sensible notification choices, and a simple weekly review.
I would recommend it to a driver who wants less mixing between gig income and personal spending, especially if a traditional bank account has become difficult to read after several shifts. I would also recommend keeping a separate record for expenses and taxes instead of expecting the card to provide a complete financial picture.
I would skip it if I already had a well-organized system that handled Uber income without friction, or if I needed advanced financial planning rather than focused earnings access. In those cases, another banking or budgeting solution may be a better center of gravity.
Overall, Uber Pro Card works best when I use it intentionally: check it at meaningful points, keep work money distinct, and avoid confusing an available balance with true profit. Its free entry, Everyone age rating, and large user base make it approachable, while its specialized design gives it a clear place in an Uber worker’s routine. My final view is positive, but practical rather than enthusiastic for its own sake: it is a useful companion for organizing Uber earnings, not a substitute for the rest of responsible money management.
Uber Pro Card FAQ
What is Uber Pro Card, and who can use it?
Uber Pro Card is a financial account and debit card designed for eligible Uber drivers and delivery people. It can help you receive earnings, manage money, and access selected features connected to your Uber work. Availability depends on your country, location, eligibility, and account status, so not every driver will see the same options during signup.
How do I sign up for Uber Pro Card?
You generally begin enrollment through the Uber Driver app or the dedicated Pro Card application flow. You may need to provide personal information, verify your identity, and agree to the account provider’s terms. Approval is not always automatic, and Uber or its financial partner may request additional documentation before activating your account and issuing a physical or virtual card.
When do Uber earnings arrive on the Pro Card?
One of the main benefits is the ability to access eligible Uber earnings quickly, sometimes shortly after completing trips or deliveries, depending on the feature and local rules. Processing times can vary because of verification, technical issues, weekends, holidays, or transaction reviews. Always check the current payout schedule and conditions shown in your app.
Are there fees for using Uber Pro Card?
The card may offer useful features without certain common banking charges, but fees can still apply in specific situations. Possible costs may involve out-of-network ATM withdrawals, international transactions, replacement cards, or other optional services. Before using the account, review the fee schedule in the app and confirm whether charges differ according to your location or account type.
Can I use Uber Pro Card like a regular debit card?
Yes, where supported, you can typically use the card for everyday purchases wherever the applicable card network is accepted. You may also be able to withdraw cash from participating ATMs and manage the account through the app. However, spending limits, merchant restrictions, ATM availability, and features such as direct deposit can vary, so review the account details before relying on it as your primary card.












